You decide one evening that you want to close a credit card. Maybe the annual fee has crept up, maybe you hold three cards and use one, or maybe you simply do not trust yourself with the limit. You call the bank, the executive tries to talk you out of it, and then nothing happens for two weeks. This is a common story, and RBI has written rules to deal with it.
The aim of this guide is simple: close the card without a surprise bill, without losing a benefit you could have used, and without a needless dent in your credit score. We cover what the RBI Directions promise you, the steps in a sensible order, what happens to rewards and auto-debits, and how to decide whether closing is even the right move.
What RBI’s rules say if you close a credit card
The current rulebook is the Credit Card and Debit Card Directions, 2025, issued by the Reserve Bank of India. Paragraph 19 deals with closure and gives you four protections worth knowing by heart.
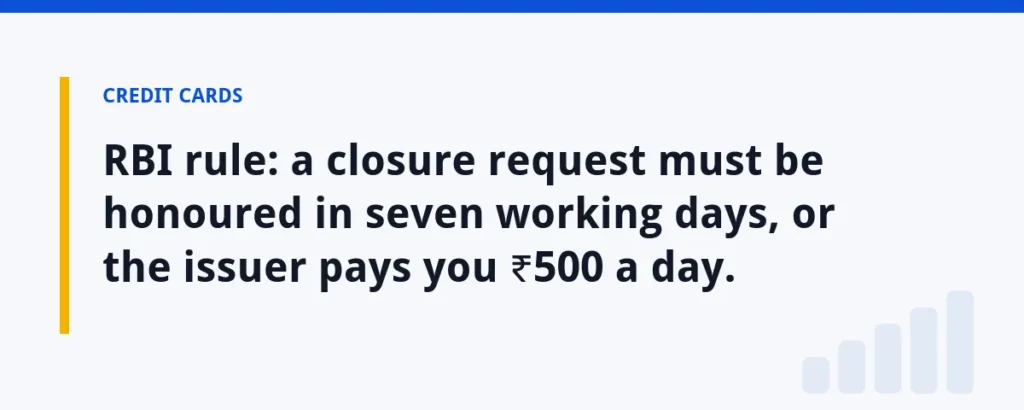
- A closure request must be honoured within seven working days, provided you have paid all dues.
- If the card issuer is late and your account has no outstanding amount, it owes you a penalty of ₹500 for every calendar day of delay.
- The issuer must offer several ways to ask for closure, such as the helpline, a dedicated email, IVR, a visible link on its website, internet banking and the mobile app. It cannot insist that you send the request by post or any other route that would slow you down.
- The closure must be reported to the credit information companies, the bureaus that keep your credit record.
As an illustration, say your request is valid, you have nothing pending, and the issuer closes the card five days after the seven working days are over. Five days at ₹500 a day means ₹2,500 payable to you. The penalty does not run while you still owe money, so clearing dues first matters.
Step 1: find out exactly what you owe
People often assume the last statement amount is the full story. It is not. Interest accrues daily on a revolving balance, new transactions may not have appeared yet, and an annual fee may have been billed since the last statement. Under the Directions, once you ask to close a credit card, the issuer must promptly tell you the outstanding dues and must not make you wait for the billing cycle to end. Use that right and ask for a written or app-based figure that includes everything up to today.
The seven working day clock does not count the days you take to pay, so pay promptly.
Things that can hide in the outstanding amount
- Interest on any balance carried from earlier months.
- Unbilled transactions, including EMI instalments that are still to fall due.
- Fees and GST on those fees.
If you have an EMI running on the card, ask what the foreclosure terms are. Some people clear it in one go, others let the EMIs finish and close the card afterwards. Our guide to credit card balance transfer and EMI conversion covers the cost side of that choice.
Step 2: use up or move your reward points
Reward points are the part where many people lose out. Here the Directions are of limited help: they define loyalty and reward programmes and ask for transparency about benefits, but they do not say what must happen to your accumulated points when you close the account. That means the answer sits in your card’s own terms and conditions.
Before you ask for closure, read the rewards section of the terms, or log in and look at your points balance and expiry dates. Then redeem what you can for vouchers, statement credit or whatever the programme allows. Also check for cashback or a fee waiver that is still pending, because those are often tied to an active card. Our guide on credit card reward points explains how points are earned, expire and are taxed.
Step 3: sort out auto-debits and subscriptions
A card that is closed cannot pay your streaming subscription, your insurance premium or your phone bill. If these payments fail, you may face a lapsed policy or a service cut. So list every recurring payment first. Your card statements for the last three or four months will show most of them.
Under RBI’s Digital Payments E-mandate Framework, 2026, you can modify the validity or withdraw an e-mandate at any time, though the change needs additional factor authentication. The issuer must send you a notice at least 24 hours before a recurring debit, and you can opt out of a single transaction or of the whole mandate. Recurring payments up to ₹15,000 per transaction can go through without extra authentication at the time of debit. For insurance premiums, mutual fund subscriptions and credit card bill payments, that ceiling is ₹1 lakh.
The practical order is: move each subscription to another payment method, confirm it has gone through once, then cancel the old mandate. Our guide on e-mandate and auto-debit shows how to view, pause and cancel them. Do not rely on the closure alone to cancel everything.
- List every subscription, insurance premium and utility on the card.
- Switch each one to a bank account mandate or another card.
- Wait for one successful cycle if the amount is large.
- Only then submit the closure request.
Step 4: ask for closure in writing
Use a channel that leaves a record. An email, a request through the app or internet banking, or a helpline call with a reference number all work. Because the issuer cannot insist on postal requests, you do not need to send a letter. If a phone executive says the card can only be closed through a branch visit, quote paragraph 19 of the Directions politely and ask for the reference number of your request.
When you ask, state your card’s last four digits, your wish to close it permanently (not block it), and that you have cleared dues or want the final figure. Ask for a confirmation message that the card is closed and the account is at nil balance.
Blocking is not closing
A blocked card can stay open as an account, and annual fees can continue. Use the word “close” and insist on a closure confirmation. Cut the physical card only after you have that confirmation.
If you hold an add-on card
The Directions say liability for dues rests solely with the principal cardholder, not with the add-on holder. If you are the principal and you close the card, the add-on card goes with it. Our guide to the add-on credit card explains how the arrangement works.
What happens to your credit score
Closing a card can affect your score through two routes. The first is utilisation, the share of your total limit that you are using. When a card goes, its limit goes too, so the same spending looks bigger against what is left. The second is history length: an older account that you paid on time adds to the length of your credit history. These two effects come from general credit-score practice and bureau commentary. The bureaus do not publish a fixed number of points, so treat any claim of an exact score drop with suspicion.
As an illustration, say you hold two cards with limits of ₹3 lakh and ₹2 lakh, and you spend about ₹1 lakh a month in total across them. Your utilisation is ₹1 lakh out of ₹5 lakh, which is 20%. If you close the ₹2 lakh card and the same spending moves to the ₹3 lakh card, utilisation becomes ₹1 lakh out of ₹3 lakh, about 33%.
| Situation | Likely effect on score | What you can do |
|---|---|---|
| Closing your oldest card | Shorter credit history over time | Keep it if it has no fee, use it once in a while |
| Closing a card with a large limit | Higher utilisation on remaining cards | Keep spending low compared with the remaining limit |
| Closing with dues unpaid | Missed payments reported, score falls | Clear dues before the request |
| Closing a newer card with a fee | Small effect, savings from the fee | Usually safe if other cards stay in good order |
When the closure shows up on your report
Our guide on how to read your credit report explains the sections.
RBI has told credit institutions and credit information companies to update credit information fortnightly, as of the 15th and the last day of each month, and institutions must send the data within seven calendar days of each reporting date. This has applied since 1 January 2025. In practice, a closure you ask for today may take a few weeks to show on your report.
So check the report about a month and a half after closure. The account should be shown as closed with a zero balance. If it still shows as open, or shows an amount overdue that you have already paid, raise it with the card issuer first and then with the credit information company that holds the record.
Cards you forgot about: closure after a year of no use
There is a rule that works in the other direction. If a card has not been used for more than a year, the issuer must notify you and start closure. If you do not reply within 30 days, the account is closed, subject to payment of all dues. Activity such as generating a statement, changing the PIN or altering transaction controls counts as use. So if you want to keep a dormant card, respond to the notice or use it.
After closure: refunds, balances and paperwork
Sometimes a card account closes with a credit balance, for example after a refund arrives late or you overpaid. The Directions require the issuer to transfer any credit balance to your bank account, and to collect the bank details from you if it does not have them. Check your statement a month later to confirm nothing is left. Also watch for a final statement or SMS: if a late charge or fee appears after closure, dispute it with the reference number you saved.
Should you close it at all?
Closing is not always the answer. If the only problem is an annual fee, ask the issuer for a waiver or a move to a no-fee variant before you close. If the issue is overspending, a lower limit might solve it without losing your credit history. If the card is old and free, keeping it with a small recurring bill paid on time costs you nothing and helps your record. If you pay a high fee for benefits you never use, or you carry a balance at a high interest rate, closing it after clearing the dues is sensible. For the cost of carrying a balance, see the guide on credit card charges, and for due dates see the guide on the credit card bill.
Use the site’s EMI calculator if you plan to convert the outstanding balance into instalments before closing, to see what the interest will really cost you.
Key takeaways
- RBI’s 2025 Directions say a closure request must be honoured within seven working days once dues are paid, with ₹500 a day payable to you for delay.
- Ask for the exact dues, including unbilled items and fees, and pay them first.
- Redeem reward points before you ask, because the Directions do not protect them.
- Move every subscription and insurance premium off the card, then cancel the old mandate.
- Ask for closure by email or app, and get a written confirmation of nil balance.
- Check your credit report after about six weeks to see the account marked closed.
- Think twice before closing your oldest, no-fee card.
This is general information, not personal advice. Terms differ between issuers, so read your own card agreement.