What happened
ICICI Bank reported a 20.1% rise in net profit to ₹14,843.03 crore for the September 2026 quarter, up from ₹12,358.89 crore a year earlier, according to Business Today. NDTV Profit and The Economic Times also reported the figure.
Net interest income (NII), the gap between interest earned on loans and interest paid on deposits, rose 17.7% to ₹25,339 crore from ₹21,529 crore.
Also read: Urban Company Q2 loss widens to ₹182 crore as revenue rises 41% · Axis Bank Q2 profit rises 38% to ₹7,003 crore; NII up 12%
Net interest margin (NIM), which measures that gap as a share of earning assets, slipped to 4.18%. It was 4.36% in the June quarter and 4.3% a year ago.
Times of India reported that consolidated net profit, which includes subsidiaries, rose 22.28% to ₹16,333.18 crore.
Income and provisions
- Non-interest income, excluding treasury, rose 12.5% to ₹8,277 crore from ₹7,356 crore.
- Fee income rose 20.1% to ₹7,795 crore from ₹6,491 crore. Retail, rural and business banking customers accounted for about 75% of fees.
- Provisions, excluding tax, were ₹851 crore, against ₹914 crore a year earlier.
The bank said the benefit of interest on tax refunds was negligible this quarter, against 8 basis points (0.08 percentage point) in the June quarter.
Asset quality
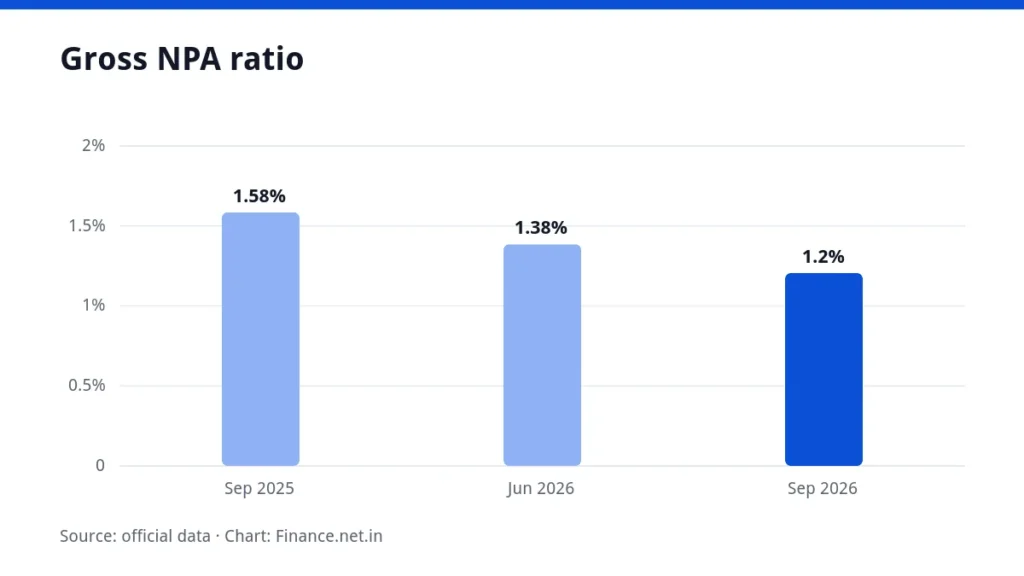
The gross non-performing asset (NPA) ratio, the share of loans where repayment has stalled, fell to 1.20% at 30 September 2026. It was 1.38% in June and 1.58% a year earlier. The net NPA ratio was 0.30%, against 0.35% in the previous quarter and 0.39% a year ago.
Gross NPA additions were ₹4,833 crore, compared with ₹5,034 crore a year earlier. Recoveries and upgrades, excluding write-offs and sales, were ₹3,620 crore. The bank wrote off gross NPAs worth ₹1,592 crore, and its provisioning coverage ratio stood at 75%.
Capital
The total capital adequacy ratio was 16.68% and the Common Equity Tier 1 (CET-1) ratio was 16.01%. The minimum regulatory requirements are 11.70% and 8.20% respectively.
The bank also bought an additional 2% stake in ICICI Life Insurance Ltd for ₹1,470 crore during the quarter.
The bank continued to hold contingency provisions of ₹13,100 crore, plus additional standard asset provisions of ₹1,283 crore made in Q3 FY26 as directed by the RBI for its agricultural priority sector portfolio.
What it means for you
If you hold ICICI Bank shares or have a deposit or loan with it, the results show strong profit growth alongside a narrowing margin. A lower margin means the bank keeps a smaller slice of each rupee lent, even as lending grows.
Cleaner loan books are also a sign that fewer borrowers are falling behind. Depositor safety is usually judged by capital buffers, and the bank’s ratios are well above the stated minimums.
Results do not change deposit or loan rates by themselves. You can check how rates affect your own borrowing with the EMI calculator.
Background
NIM is closely watched for banks because it shows how profitable core lending is. The Economic Times reported that the bank expects the margin to come under more strain in the December quarter. The reasons given were the cost of raising dollar-denominated deposits from non-resident customers and the expense of opening more branches.
For related earnings coverage, see Wipro’s Q2 results.